
Resale Value and Financing Options
Navigating the used car market can be complex, and understanding vehicle titles is a critical part of the process. A salvage title is issued when an insurance company declares a vehicle a total loss due to damage from an accident, flood, theft, or other major event. While the significantly lower price tag on these vehicles can be tempting, it comes with important considerations. A salvage title history dramatically impacts a car's resale value, making it harder to sell in the future and for a much lower price than a comparable vehicle with a clean title. Furthermore, securing financing and insurance for a car with a branded title presents unique challenges. Lenders and insurers view these vehicles as higher risk, which can lead to loan denials or more expensive, limited coverage options. Understanding these factors is essential before you consider purchasing a vehicle with a salvage history.
While a vehicle with a salvage or rebuilt title can be an affordable option, the path to ownership is filled with hurdles. The immediate savings on the purchase price are often offset by a steep drop in resale value, making it a poor long term investment. Financing is a major obstacle, as most traditional lenders are hesitant to approve loans for vehicles they deem to have an uncertain value and potential safety risks. Before making a decision, it is crucial to weigh the initial cost savings against future financing difficulties and diminished resale potential.
A Deep Dive into Salvage Titles and Their Financial Implications
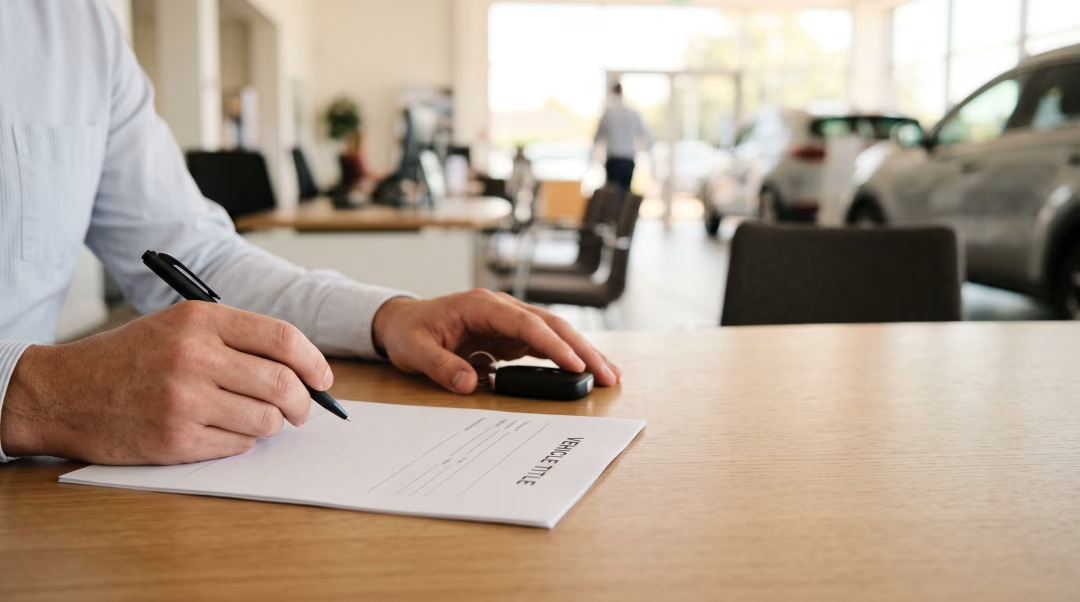
When a vehicle is involved in a significant incident like a major collision, flood, or is recovered after being stolen, an insurance company assesses the cost of repairs. If the repair cost exceeds a certain percentage of the vehicle's actual cash value (ACV)—a threshold that varies by state, typically from 70% to 95%—the insurer will declare it a "total loss." At this point, the insurance company pays the owner for the vehicle's value and takes possession of it. The state's Department of Motor Vehicles (DMV) then rebrands the original clean title to a "salvage" title. This permanently marks the vehicle's history, signaling to all future owners that it was once deemed too damaged to be worth repairing by an insurer.
Salvage vs. Rebuilt: A Critical Distinction
It is important to understand that you cannot legally drive a car that has a salvage title on public roads. A salvage title simply indicates the vehicle is in a state of disrepair and is not roadworthy. For the car to become drivable again, it must be repaired and pass a rigorous state inspection process. Once it successfully passes this inspection, which verifies that the vehicle is safe to operate, the DMV will issue a new title, most commonly known as a "rebuilt" or "reconstructed" title. While a rebuilt title makes the car legal to drive, register, and insure, it does not erase its past. The history of the salvage event remains permanently attached to the vehicle's record, which is readily available on any standard vehicle history report.
The Unavoidable Impact on Resale Value
The primary consequence of a salvage or rebuilt title is a significant and permanent reduction in the vehicle's market value. Industry experts generally agree that a rebuilt title can decrease a car's value by 20% to 40% compared to an identical model with a clean title. This substantial drop in value is due to several factors:
- Perceived Risk: Buyers are naturally wary of a vehicle with a history of severe damage. There is always a risk of underlying issues that were not properly addressed during the repair process, which could lead to expensive mechanical or structural problems down the road.
- Smaller Buyer Pool: Many potential buyers will immediately filter out any vehicle with a branded title, regardless of the quality of the repairs. This dramatically shrinks the market for your vehicle, forcing you to lower the price to attract the remaining interested parties.
- Difficulty in Trading In: Dealerships are often reluctant to accept vehicles with rebuilt titles as trade-ins. If they do, the trade-in value offered will be exceptionally low due to the challenges they will face in reselling it. This can complicate the process of upgrading your vehicle, and you can explore potential trade-in values with tools like our Value My Trade estimator.
The Challenge of Securing Financing
Obtaining an auto loan for a vehicle with a rebuilt title is one of the biggest hurdles prospective buyers face. Most major banks and traditional auto lenders have policies against financing these vehicles. The reason is simple: the loan is secured by the vehicle itself, which serves as collateral. A rebuilt title introduces significant uncertainty about the vehicle's true value and structural integrity.
Lenders worry that in the event of a default, they will be unable to recoup their losses by repossessing and selling a car with a diminished and unpredictable value. While not impossible, finding financing typically requires looking beyond traditional sources. Some credit unions or specialized lenders may be willing to consider a loan, but they will almost certainly require a comprehensive mechanical inspection, detailed documentation of all repairs, and a larger down payment to mitigate their risk. Interest rates for these loans are also likely to be substantially higher. If you're exploring options, you can always begin by filling out one of our applications to see what may be possible.
Insurance Complications and Limitations
Just like lenders, insurance companies are cautious when it comes to vehicles with a rebuilt title. Before you can even get a quote, most insurers will demand a statement from a certified mechanic confirming the vehicle is in sound condition, along with photos and receipts for the repair work. Even if you provide this information, your coverage options may be limited. Many companies will only offer liability coverage, which covers damage to other vehicles and property but not to your own car. Finding an insurer willing to provide full coverage (comprehensive and collision) can be difficult, and if you do, the premiums will likely be higher than for a similar car with a clean title. This is because the insurer has no reliable way to determine the vehicle's replacement value in the event of another total loss.
What to Do Before You Buy
If you are still considering a vehicle with a rebuilt title, it is imperative to perform thorough due diligence to protect yourself. Before making any commitment, follow these essential steps:
- Get a Pre-Purchase Inspection (PPI): This is the most important step. Hire an independent, certified mechanic who specializes in body and frame work to conduct a thorough inspection of the vehicle.
- Review All Documentation: Ask the seller for the complete repair history, including receipts for parts and labor, and pre-repair photos of the damage if available.
- Secure Financing and Insurance Quotes: Do not wait until after you have agreed on a price. Contact lenders and your insurance agent beforehand to confirm that you can get a loan and the necessary coverage for that specific vehicle.
- Run a Vehicle History Report: Use a reputable service to get a full report on the vehicle's past, which will confirm the salvage event and may provide additional details about the damage.
Ultimately, a vehicle with a rebuilt title can offer a low entry price, but it comes with a legacy of risk that affects its value, financeability, and insurability for the rest of its life. If you have questions about a specific vehicle in our used inventory or need more information, do not hesitate to contact us. Our team is here to provide transparent answers to help you make an informed decision.
What is the difference between a salvage title and a rebuilt title?
A salvage title is issued when a vehicle is declared a total loss and is not legal to drive on public roads. A rebuilt title is issued after a salvage vehicle has been repaired and passed a state safety inspection, making it roadworthy again. However, the history of the salvage event remains on the vehicle's permanent record.
Can I get a traditional auto loan for a car with a rebuilt title?
It is very difficult. Most major banks and traditional lenders will not finance a vehicle with a rebuilt title because its value and structural integrity are considered uncertain. The vehicle serves as collateral for the loan, and lenders view it as too high of a risk. You may have better luck with credit unions or specialized subprime lenders.
How much does a salvage history devalue a car?
A rebuilt title typically reduces a vehicle's market value by 20% to 40% compared to an identical model with a clean title. The exact amount depends on the vehicle's make and model, the type of original damage, and the quality of the repairs. This depreciation is permanent and will affect the car's value for its entire lifespan.
Is it ever a good idea to buy a rebuilt title car?
It can be, but only for the right buyer under the right circumstances. If you are a skilled mechanic, have the vehicle thoroughly inspected by a trusted professional, plan to keep it for a long time, and are comfortable with the financing and insurance challenges, the lower purchase price might be worth it. For the average car buyer, it is generally a risky proposition.
How can I find out if a car has a salvage title in its past?
The best way is to obtain a comprehensive vehicle history report from a reputable provider like CarFax or AutoCheck using the vehicle's VIN. This report will detail any title branding events, including salvage declarations, in the vehicle's history. Sellers are legally required to disclose a branded title, but a history report provides third party verification.
