
Installing a Payment Assurance Device
For dealerships offering in-house financing, managing portfolio risk is a top priority. Payment assurance devices, such as GPS trackers and starter interrupt systems, have become essential tools in this process. These technologies provide a layer of security, aiding in vehicle location for payment reminders and, if necessary, recovery. However, implementing them is not as simple as just choosing a vendor and installing hardware. Before you proceed, it is critical to understand the full scope of what is involved. This includes navigating a complex web of legal regulations, establishing clear operational procedures, and developing a transparent communication strategy for your customers. A well-planned approach ensures you can leverage these devices effectively to protect your assets while maintaining positive customer relationships and staying fully compliant. A hasty decision can lead to significant legal exposure and operational headaches that far outweigh the benefits.
Successfully integrating payment assurance technology into your dealership's operations is a strategic decision that extends beyond the service bay. The true value is realized when the hardware is supported by robust internal policies, comprehensive staff training, and an unwavering commitment to legal and ethical standards. This technology can significantly improve payment compliance and simplify asset recovery, but only when used responsibly. It requires a thoughtful balance between protecting your portfolio and respecting customer privacy, ensuring every action taken is both effective and compliant.
Understanding Payment Assurance Technology
At its core, a payment assurance device is a piece of hardware installed in a vehicle that gives a lender or dealership specific capabilities related to the vehicle's location or operation. This technology is most common in the subprime and Buy Here, Pay Here (BHPH) sectors, where it serves as a tool to mitigate the higher risks associated with these loans. There are two primary types of devices that fall under this category, each serving a distinct but related purpose.
- GPS Trackers: These devices use the Global Positioning System to provide real-time or periodic location data for a vehicle. This information is invaluable for collections efforts, allowing staff to confirm a vehicle's location before sending payment reminders or dispatching a recovery agent. Modern trackers are compact, reliable, and come with features like geofencing alerts (notifying you if a vehicle leaves a designated area) and low-battery warnings.
- Starter Interrupt Devices (SIDs): Often integrated with GPS functionality, an SID gives the lender the ability to remotely prevent a vehicle from starting. It does not shut off a running vehicle, which would be a major safety hazard. Instead, once the vehicle is turned off, the device can be activated to prevent the ignition from engaging. This is a powerful collections tool, but its use is heavily regulated and requires careful consideration.
The goal of this technology is not just to simplify repossession. More importantly, it acts as a deterrent to default and a tool for communication. A simple payment reminder tone from the device or a notification sent to a customer's phone can often prompt a payment before an account becomes seriously delinquent. It helps in building a more efficient collections process.
Navigating the Legal and Compliance Landscape
Implementing payment assurance devices without a thorough understanding of the legal requirements is a significant risk. The laws governing their use are complex and can vary dramatically by state. Failure to comply can result in severe fines, lawsuits, and damage to your dealership's reputation. Before you install a single device, you must prioritize compliance.
The most important element is disclosure. You must obtain clear, unambiguous, and written consent from the customer before installing any tracking or disabling device. This disclosure should be a distinct part of the financing agreement and must clearly state what the device is, what it does, and under what circumstances it will be used. Hiding these terms in fine print is not acceptable and will not protect you legally. Consult with a qualified attorney to ensure your contracts and disclosure forms are compliant with all relevant regulations, including state-specific laws and federal rules from the FTC. For more information on legal topics, explore our pages on repossession laws by state and the importance of adhering to data privacy rules.
Choosing the Right Device and Vendor Partner
The market for payment assurance devices is crowded, and not all providers are created equal. Selecting the right technology and partner is a critical step that will impact your operational efficiency, costs, and overall success with the program. Rushing this decision can lead to unreliable hardware, poor support, and hidden fees. A thorough evaluation process is essential. You can learn more by reading our BHPH GPS vendor comparison guide.
When vetting potential vendors, consider the following key factors:
- Hardware Reliability: The device must be durable and perform consistently. Ask about failure rates, warranty coverage, and resistance to tampering. A device that frequently fails or is easily disabled is worthless.
- Software Platform: The user interface should be intuitive and easy for your staff to learn. Look for robust reporting features, reliable alert systems, and seamless integration capabilities with your existing Dealer Management System (DMS).
- Customer Support: When a device is offline or you are facing a critical recovery situation, you need immediate and effective support. Evaluate the vendor's support hours, response times, and the technical expertise of their team.
- Data Security: The vendor will be handling sensitive customer and vehicle location data. Inquire about their data security protocols, encryption standards, and overall compliance with privacy regulations.
- Transparent Pricing: Understand the full cost structure. This includes the price of the hardware, monthly service fees, activation fees, and any charges for specific features like starter disable commands. Avoid vendors with complex or confusing pricing models.
Installation, Training, and Customer Communication
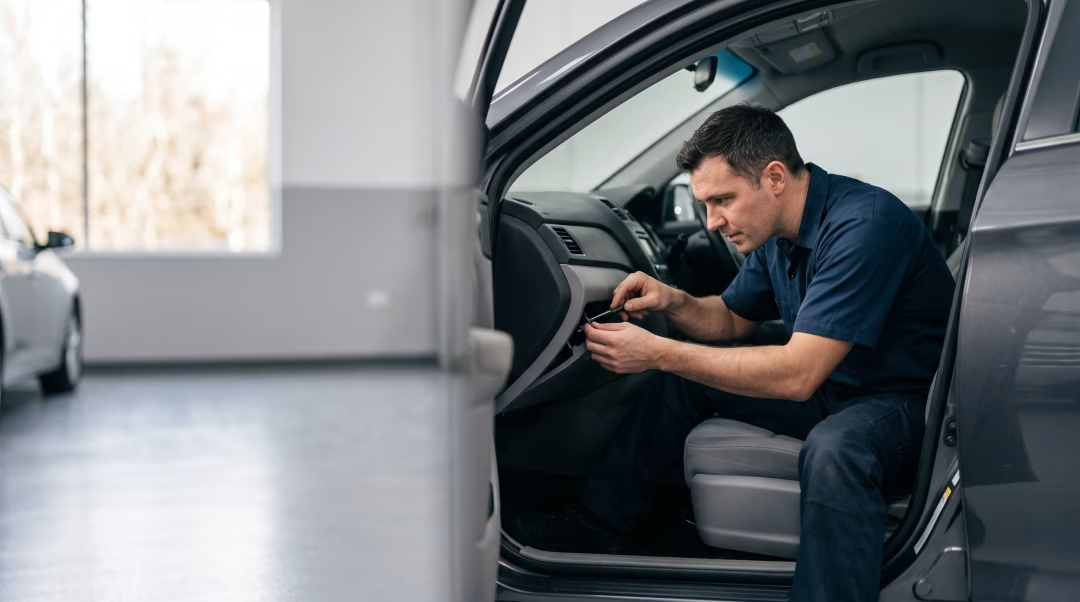
Once you have selected a vendor, the focus shifts to implementation. A professional and covert installation is crucial. If a device is easy to find, it is easy to remove or disable. Whether you use in-house technicians or a third-party service, ensure they are trained on proper placement to maximize signal strength and minimize the risk of detection.
Equally important is staff training. Your sales team must be coached on how to explain the device to customers in a positive and transparent manner. Frame it not as a punishment, but as a tool that enables the dealership to offer financing to a wider range of credit profiles. The collections team needs rigorous training on the platform's features and, most importantly, on the dealership's policies for using them. Clear guidelines must be established for when and how location data can be accessed and under what specific conditions a starter interrupt command can be sent. This ensures consistent, compliant, and ethical use of the technology across your entire team. For more on our team, you can meet our staff online.
Frequently Asked Questions
Are payment assurance devices legal to use?
Yes, payment assurance devices are legal in most states, provided the dealership follows strict legal guidelines. The most critical requirement is obtaining explicit, written consent from the customer before installation. This disclosure must be clear and detailed in the financing contract, explaining the device's function and purpose. Laws vary significantly by state, so consulting with a legal professional is essential to ensure your contracts and practices are fully compliant.
Will a GPS tracking device drain my vehicle's battery?
High-quality, modern GPS tracking devices are engineered to be extremely low-power. They are designed to enter a "sleep" mode when the vehicle is not running and only draw a very small amount of power to maintain their connection. On a vehicle with a healthy battery, the impact is negligible and will not cause it to drain. Reputable vendors design their products specifically to avoid this issue.
What is the difference between a GPS tracker and a starter interrupt device?
A standard GPS tracker only reports the vehicle's location. A starter interrupt device (SID) includes GPS tracking but adds the functionality to remotely prevent the vehicle's engine from starting. An SID cannot and will not shut off a vehicle that is already in motion, as this would be a major safety risk. Its function is to prevent ignition after the car has been turned off, serving as a powerful tool for collections on delinquent accounts.
Do dealerships have to tell customers a device is being installed?
Absolutely. Transparency is not just good business practice, it is a legal necessity. Failing to disclose the presence of a tracking or disabling device can lead to serious legal consequences. The customer must be informed and provide written consent as part of the financing agreement. This disclosure should clearly outline what the device does and the policies governing its use by the dealership.
How does this technology help me secure financing?
For lenders and dealerships, financing a vehicle for a customer with a challenging credit history presents a higher level of risk. A payment assurance device helps mitigate that risk by improving the chances of recovering the asset in case of a loan default. By reducing their potential losses, this technology gives dealerships the confidence to approve financing for individuals who might otherwise be turned down by traditional lenders, expanding access to vehicle ownership.
